
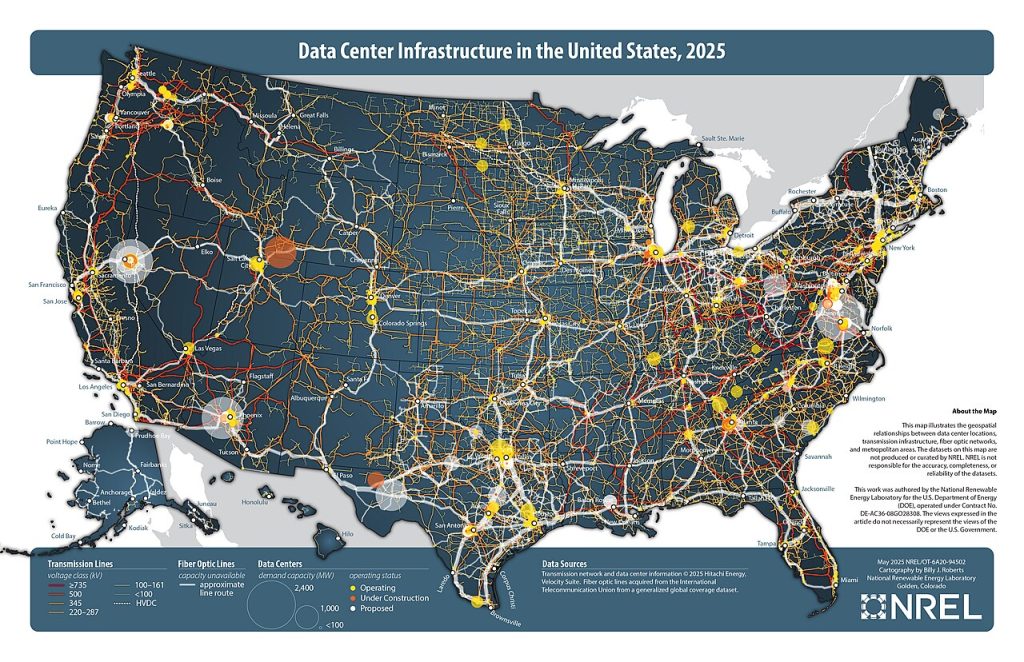
Building a data center is a strange kind of expense. You pay enormous sums up front for land, power connections, buildings, cooling and thousands of servers, and then you earn the money back slowly, customer by customer, over years. Few companies can fund that from the cash left over at the end of a quarter. That is why big technology firms, including long-established enterprise software and cloud providers, regularly show up in the market for corporate bonds.
What selling corporate bonds actually means
Corporate bonds are loans split into small pieces. A company agrees to pay a fixed interest rate for a set period and return the principal at the end. Investors such as pension funds, insurers and asset managers buy these pieces because they want steady income. Banks usually help arrange the sale and find buyers.
Unlike selling shares, borrowing doesn’t dilute existing owners. The company keeps control and promises repayment. For a business with predictable cash flows, that can be cheaper than raising equity, especially when interest rates are favorable.
A fair question is why a company would sell corporate bonds when it could ask a bank for a loan. The answer is mostly scale and flexibility. A single bank rarely wants to hold a loan as large as a data center program requires, while a bond can be spread across many investors at once. Bonds also tend to carry fewer restrictions on how the business is run, though they come with legal terms of their own that issuers must follow.
Timing matters too. Companies often sell corporate bonds when markets are calm and rates look acceptable, even before they have spent the money. Holding cash raised in advance can look wasteful, but it gives the company room to start building without waiting for the next market window.
Why this path suits infrastructure
Cloud computing is capital hungry. Demand for AI workloads has pushed the cost of new capacity higher, a theme explored in what it takes for a country to build its own AI compute, since specialized chips and power-hungry facilities are expensive. Companies that want to compete for customers must build before the revenue arrives, a bit like a shipping line ordering vessels in advance of cargo.
Debt matches this pattern. Long-lived assets can be paid for by long-dated borrowing, spreading cost across the years in which the assets produce income. Companies often issue bonds in several maturities, so repayments don’t all land at once.
How investors read the deal
When a large issuer announces a sale of corporate bonds, the market looks at a few things.
- Credit rating. Agencies assess how likely the company is to repay. Higher ratings mean lower interest costs. A heavy borrowing spree can put a rating under pressure.
- Leverage. How much debt the company carries relative to its earnings and cash flow.
- Coverage. Whether operating income comfortably exceeds interest payments.
- Use of proceeds. Is the money for growth, refinancing old debt, buying another company or returning cash to shareholders? Growth investment usually reads better than a purely financial move.
- The spread. The extra yield over government bonds shows how much risk buyers think they’re taking.
Demand also tells a story. A heavily oversubscribed sale suggests investors trust the company. Weak demand may force a higher rate.
The risks nobody should wave away
Borrowing is a bet that future revenue will cover the cost. If demand for cloud or AI services grows more slowly than planned, the company still owes its interest. Heavy investment cycles have burned industries before: telecom firms in the late 1990s built networks faster than customers appeared, and some of them didn’t survive the debt. Technology is not immune to that pattern, though today’s largest players generally have strong existing businesses to lean on.
For the borrower, there’s also the matter of flexibility. Interest payments are a fixed commitment, and a downturn doesn’t pause them. Rating downgrades make later borrowing costlier. Companies manage this by laddering maturities, keeping cash reserves and watching their ratios closely.
It helps to picture a repayment ladder. Suppose a company sells corporate bonds that mature across several different years, some short, some long. Each year only a slice comes due, and the company can repay it from earnings or refinance it by selling new bonds. That staggering is one of the quiet reasons large borrowers can carry heavy debt without a single crisis date. The danger is a year when markets are closed and a large slice comes due anyway.
What it means for ordinary readers
If you work in or around enterprise technology, a big sale of corporate bonds is a hint about strategy. A burst of borrowing often signals a coming expansion in capacity. For customers, it could mean new regions, more availability and perhaps more competitive pricing. For employees and suppliers, it suggests where investment and hiring may land, though borrowing and layoffs can happen together, as in this look at record revenue alongside job cuts.
If you hold index funds or a pension, you may own pieces of these corporate bonds without knowing it, which is another reason to care about how well the money gets used.
The takeaway is not to panic or celebrate at any headline number. Look at what the debt is paying for, what the business earns, and how comfortably it can handle the bill. Those three facts are worth more than the size of the offering.
Image: DOE/National Renewable Energy Laboratory (NREL) / Wikimedia Commons, Public domain.



