
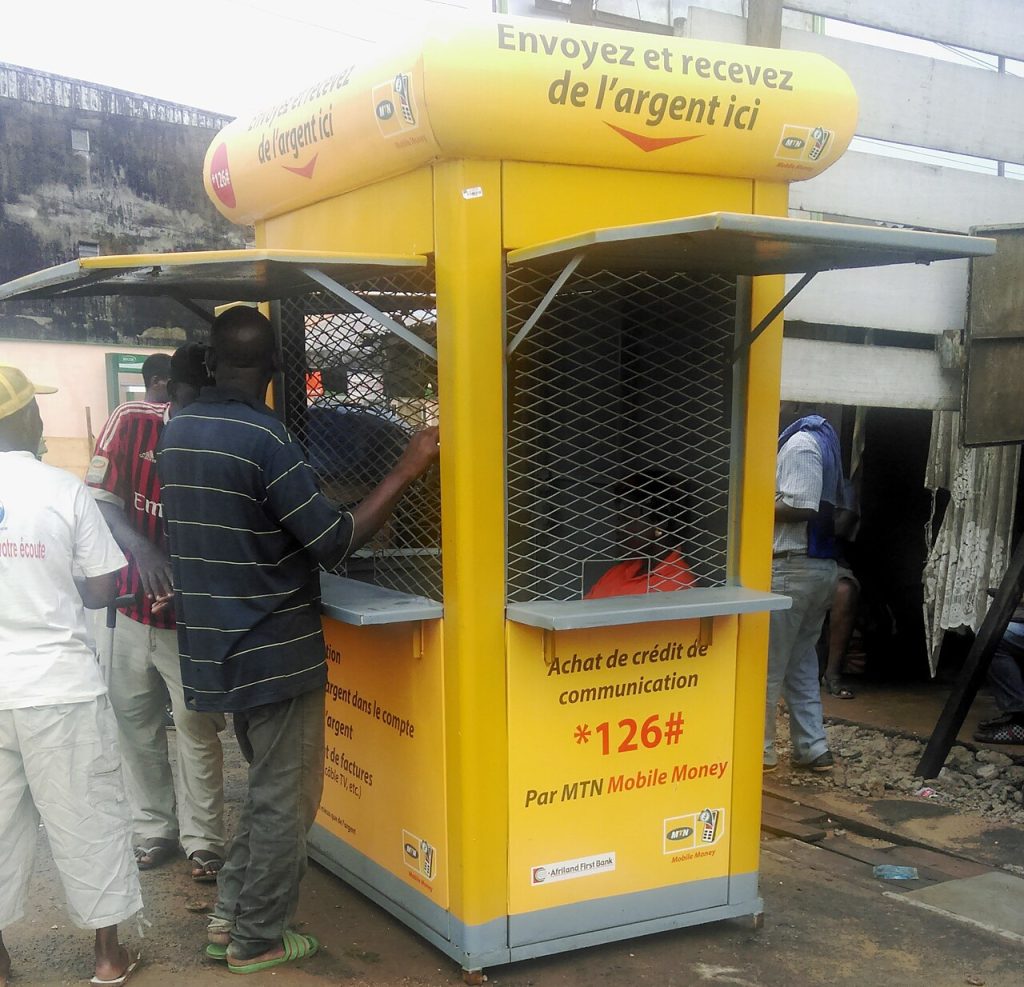
When a payments company is said to be worth billions, the number tends to travel faster than the explanation. It shows up in headlines, gets repeated in pitch decks, and soon sounds like a fact about the business. It isn’t. A valuation is a negotiated price, and understanding how it gets built tells you a lot about what investors think African payments startups are really selling.
Volume is not revenue
Start with a distinction that trips up many readers. A payments company may process a huge amount of money, but it keeps only a sliver of it. That sliver is the take rate: the percentage of each transaction that stays with the company after paying banks, card networks and mobile operators their share. On a card payment the take rate can be small, since much of the fee goes to others in the chain.

So an investor looks at total payment volume first, then asks how much is net revenue after those pass-through costs. A company with enormous volume and a thin margin can be worth less than a smaller one that sells software, fraud tools or lending on top of the payments flow.
Why growth gets paid for in African payments startups
Valuation in a young market is mostly about the future. Many African economies still rely heavily on cash, so African payments startups build for a market where card and mobile money penetration varies widely. A payments company that connects merchants to customers across several countries is betting that more of that cash will become digital. Investors pay today for the share they believe the company will hold when that happens.
That bet has risks the numbers do not always show. Currencies can swing sharply, which makes revenue earned in one country worth less when converted. Regulators in each market have their own licensing rules. And a company that expands into ten countries has to maintain ten sets of banking relationships, each with its own quirks.
A simple example shows why this matters. Imagine two companies that each process the same amount of money in a year. One keeps a tiny slice because most of its fees pass straight to banks and networks. The other keeps a larger slice because it also sells fraud screening, payouts and working-capital loans to the same merchants. Investors will usually put a higher multiple on the second, even though the raw volume is identical. Among African payments startups, the quality of revenue counts for more than its size.
Multiples are also borrowed from elsewhere. Analysts often compare a company with listed payments firms in other regions, then adjust for riskier currencies, thinner banking infrastructure and faster growth. That adjustment is a judgment call, which is exactly why two investors can look at the same company and disagree by a wide margin.
What investors actually check
- Net revenue growth: how fast the part the company keeps is rising, not just the gross flow.
- Concentration: whether a few large merchants account for most of the volume. Losing one could dent the whole business.
- Margins and costs: fraud losses, chargebacks, and the price of moving money across borders.
- Product breadth: whether the company has added things like payouts, invoicing or merchant lending that increase revenue per customer.
- Compliance record: licenses held, audits passed, and how regulators view the company.
The role of strategic backers
Sometimes a funding round includes a backer from outside traditional venture capital, such as a crypto or fintech company, a card network, or a bank. These investors may care about more than financial return. They may want a distribution partner, access to a market, or a foothold for their own products. That can make a round more valuable than the cash alone, but it can also complicate a later sale, because rivals of the backer may hesitate to buy the company.
It is worth reading these deals as partly commercial and partly financial. The money pays for growth. The relationship may shape what the company can do next.
Reading a valuation headline for African payments startups
Treat a stated valuation as one input. First, it is usually a post-money figure, meaning it includes the new cash. Second, the terms attached matter: investors may hold preferences that pay them first in a sale, which means common shareholders and employees could receive less than the headline suggests. Third, private valuations are not marked daily. They reflect a deal at a moment, and conditions can change. Markets that celebrated rapid growth in one year have often demanded profitability in the next.
It also helps to ask what proof sits behind the price. Audited financials, disclosed revenue and profit, and a believable path to an exit give the number weight. A price based mainly on volume and ambition deserves more skepticism.
For merchants and customers of African payments startups, the number matters less than the product. A well-funded company may cut fees or expand into new countries, but a high valuation also creates pressure to grow quickly, which can push prices up later. To see how a price ends up in ownership records, our explainer on cap tables and secondaries is a good next read, and the piece on why tap-to-pay limits exist covers the consumer side of the same payment rails.
For a neutral definition of the term itself, see the general article on valuation in finance.
What it means for African payments startups
For founders, a high valuation is both fuel and pressure. It signals confidence, attracts talent and partners, and lets the company spend on expansion. It also sets a bar that later rounds must clear, and missing it can hurt. For everyone else, the useful takeaway is that payments is a slow, regulated, margin-sensitive business, and the companies that last tend to be those that earn money from more than the transfer itself.
Image: Minette Lontsie / Wikimedia Commons, CC BY-SA 4.0.


