A standard car policy is built for the average driver, but auto insurance for high networth individuals has different priorities. When you own valuable cars, a large home and substantial savings, the biggest risk is not a dented bumper but a lawsuit after a serious accident. Here is a practical guide to what to look for.
Why standard limits may not be enough
If you cause a crash that injures several people, a court could award more than a basic policy covers. The excess can be claimed from your personal assets. Someone with significant savings, investments and property is an attractive target. That is why wealthier drivers usually want higher liability limits and extra layers of protection.
Key features of auto insurance for high networth individuals
High liability limits
Many private-client insurers offer limits of $500,000 per person or more, and some go further, usually in combination with umbrella cover.
Umbrella liability
An umbrella policy sits on top of your auto and home policies and pays out once their limits are exhausted. Policies commonly begin at $1 million of coverage, and each extra million costs comparatively little. Insurers often require you to maintain minimum limits on the underlying auto policy.
Agreed-value coverage
For classic, exotic or customised vehicles, ordinary “actual cash value” can leave you short. Agreed-value policies set a value in advance and pay that amount in a total loss.
Choice of repairs
Premium insurers often let you choose a specialist body shop and original manufacturer parts, which can matter for luxury or electric vehicles.
Rental and concierge services
Some private-client policies include replacement vehicles of similar quality and dedicated claims handlers.
Who sells it
Private-client divisions of large insurers, such as Chubb, PURE and others, specialise in higher-value households. Specialist collector car insurers, including Hagerty, cover classic vehicles. Independent agents who work with several insurers can compare quotes.
Other points to consider
- Drivers in the household. Teen drivers raise risk, so ask how the policy handles them.
- Uninsured and underinsured motorist cover. It protects you if the other driver has little insurance.
- Where the car is kept. Garage security can lower premiums.
- Claims history. A clean record matters more at higher limits.
Cost considerations
Premiums for high-value cars and big limits are higher, but umbrella cover is often surprisingly cheap relative to the protection. Getting quotes from several insurers and bundling home, auto and valuables with one company can reduce costs. A high deductible can also lower the price if you can afford to pay a larger share of small claims.
Linking cover to your wider plan
Insurance is one part of a broader wealth plan. Our overview of high net worth tax planning and the guide to private banking services cover other parts of the picture.
Quick questions readers ask
Do I need an umbrella? Many advisers recommend one once your assets exceed your liability limits. Is agreed value worth it? For rare cars, yes. Can a lawyer help? Yes, for complex situations.
Questions to ask an insurer
Before you sign, ask how claims are handled for luxury and electric vehicles, whether original parts are guaranteed, and how quickly a loss is paid. Ask whether you get coverage if someone drives your car with permission, how the policy treats cars used for business, and what the exclusions are. Request a written comparison of limits and deductibles from at least two insurers. A good broker will welcome these questions, and the answers often reveal real differences between providers that headline prices do not show.
The conclusion
Auto insurance for high networth individuals is about protecting your wealth from a single accident as much as repairing a car. Higher limits, an umbrella policy and agreed-value cover are the main tools, and a good broker will tailor them to your situation.
This is general information, not insurance, legal or financial advice.
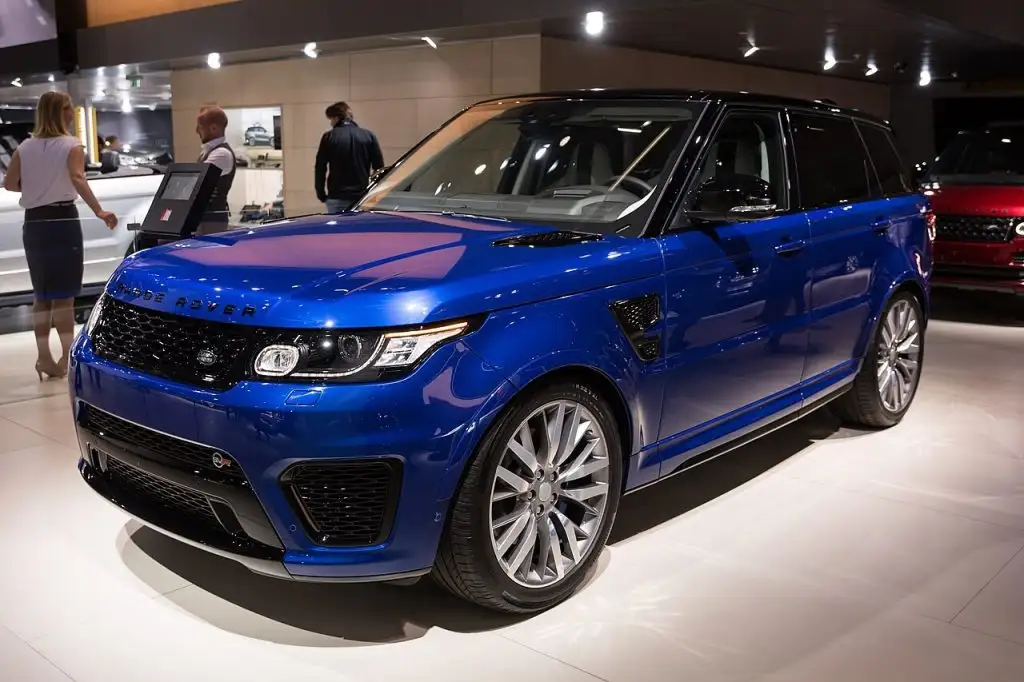
Featured image: Range Rover Sport SVR, IAA 2017, Frankfurt (1Y7A3071).jpg by Matti Blume, CC BY-SA 4.0, via Wikimedia Commons.